What we do
Full-service assurance, tax, and advisory.
From statutory audit to strategic advisory, our engagements are built on rigor, ethics, and a genuine understanding of your business.
Audit & Assurance
- Financial statements audit
- Internal audit
- Review of historical financial statements
- Review of prospective financial statements
Tax Services
- Tax assessment
- Tax compliance health check
- Tax due diligence
- Tax opinions and rulings
- Tax planning and structuring
- Estate and donor’s tax compliance
Accounting Services
- Bookkeeping
- Compilation of financial statements
- Account reconciliations
- Internal accounting
Advisory & Business Consultancy
- Business policy making
- Financial due diligence
- Risk management
- Strategic management
Corporate Services
- Business registration
- Corporate structuring
- Corporate secretarial
- Payroll processing and compliance
Other Services
- Agreed-upon procedures
- Company profiling & loan application assistance
- Estate planning · Retirement planning and funding
- Contract review · Collection services
- Real estate services and other allied services
Who we serve
Industries we serve.
The reporting framework, the controls, and the regulator differ by sector. Our engagements cover twelve.
Beyond Tacloban City
Engagements run from wherever you are.
Clients elsewhere in Eastern Visayas, in Metro Manila and in other regions work with us without travelling to our office.
Documents turned over online
Records, schedules and supporting documents are exchanged through shared online folders, and reports are delivered the same way.
Meetings by video call
Planning, status and closing meetings are held by video call. Visits are scheduled where the work requires them, such as an inventory count.
Electronic filing
Returns and reports are filed through the online systems of the BIR, the SEC and the other agencies that accept them.
Our Partners
Led by credentialed professionals.
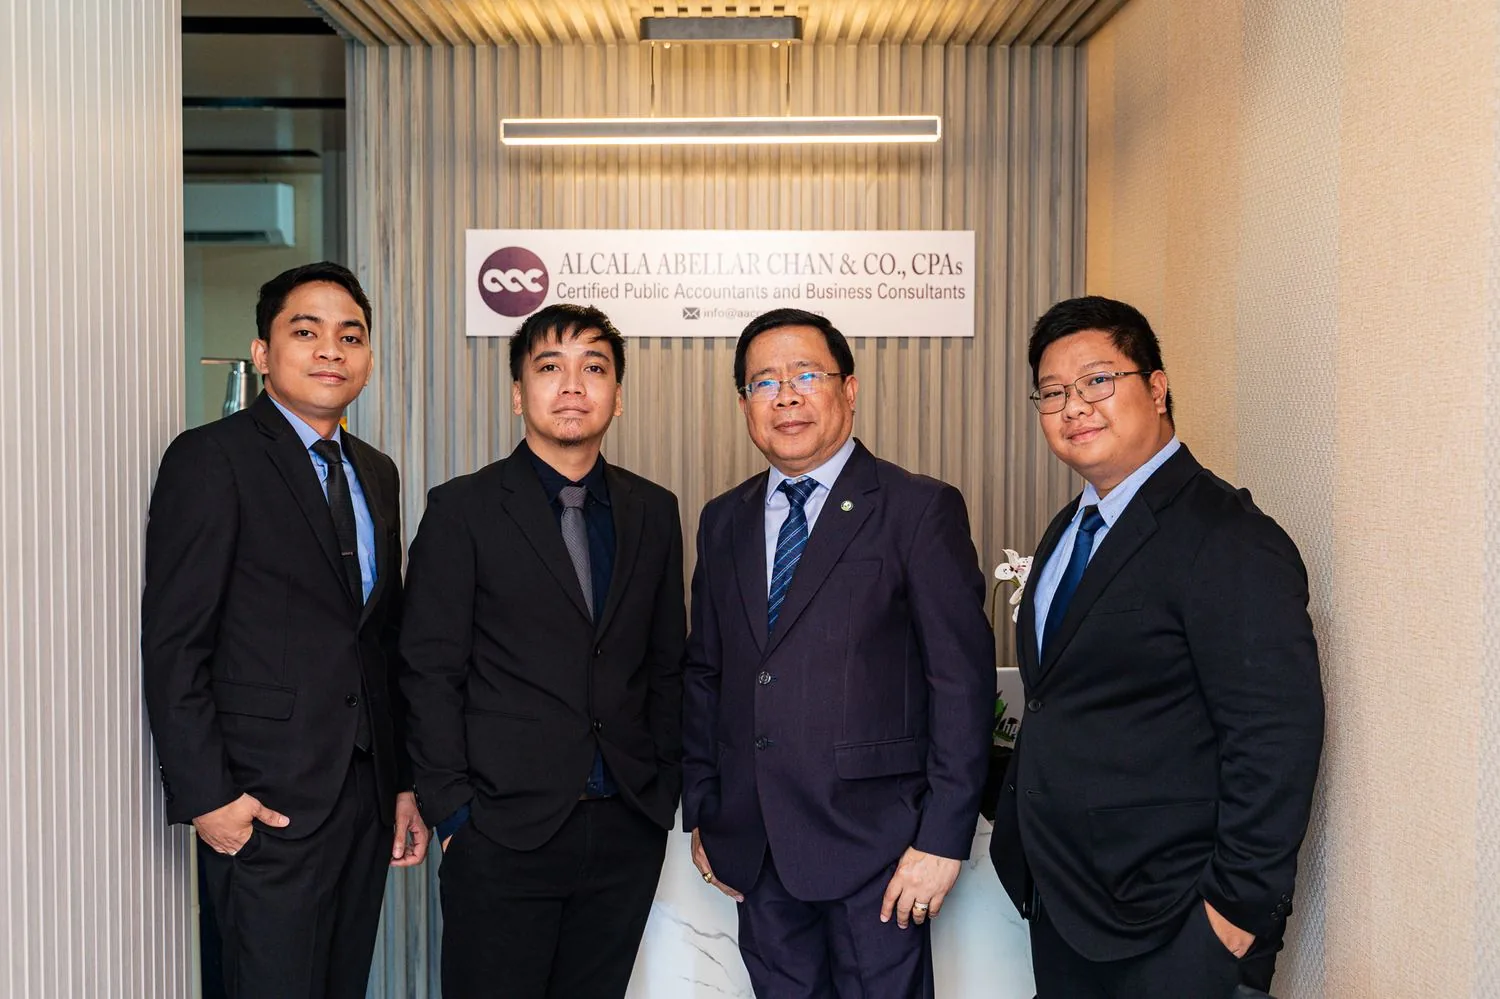
Four partners with national distinctions, international practice, and deep roots in the academe.
Placed 2nd in the May 2018 CPA licensure examination. Trained in assurance and taxation at one of the largest professional services firms in the world before returning to Region VIII, and has since audited MSMEs through to large corporations. Assists taxpayers through BIR audits and assessments. Teaches audit, assurance, and taxation, and authored a CPA reviewer book on auditing.
View full profile →
Audit and Professional Practice Director at one of the world’s Top 4 professional services firms, serving in its London, New York, and Philippine offices. Sat three consecutive terms on the Audit and Assurance Standards Council, served as National President of PICPA for FY 22-23, and sits on the council of the ASEAN Federation of Accountants. Led Saint Paul School of Professional Studies as President for more than a decade.
View full profile →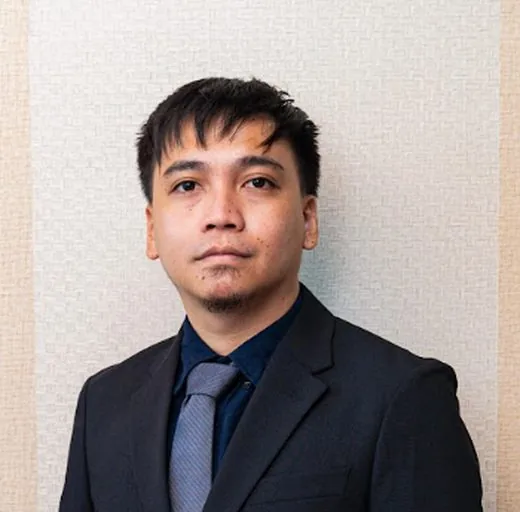
Placed 1st in the May 2018 CPA licensure examination and 10th in the December 2023 Bar. Practice centres on tax compliance and health checks, assistance with tax audits, corporate structuring, and tariff and customs compliance. Began his career as a risk and compliance officer, internal auditor, and data privacy officer. Lectures on taxation and commercial law and reviews for the CPA board examinations.
View full profile →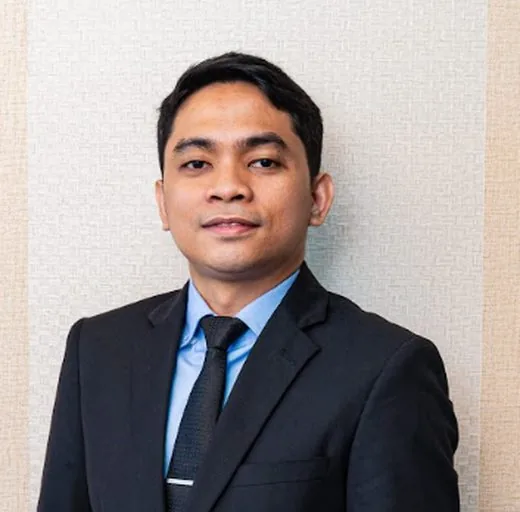
More than half a decade in the public practice of accountancy, auditing MSMEs and large corporations across retail and trade, educational institutions, non-profits, importation, and services. Began as an audit associate at a Manila firm. Works in full-cycle accounting and financial reporting with variance and ratio analysis. School accountant and part-time lecturer at SPSPS, and treasurer of PICPA–Tacloban Chapter.
View full profile →Insights
What falls due this month.
The next filing and payment deadlines we are tracking. Open the calendar for the full year.
Get in touch
Let’s talk about your business.
Tell us what you need — audit, tax, bookkeeping, or advisory — and our team will get back to you.
2nd Floor, Rubber Tree Building, Brgy. 77, 611 BLISS – Fatima Diversion Road, Tacloban City, Philippines 6500
Suite 302, F. Mendoza Complex, Sto. Niño St., Brgy. 28, Tacloban City 6500
0995 398 9482
info@aaccocpas.com
Message us on Messenger
Insights
AAC Tax Code.
The National Internal Revenue Code of 1997 as it currently stands — consolidated by the firm to carry the TRAIN Law, the CREATE Act, the Ease of Paying Taxes Act, the VAT on Digital Services Act, CREATE MORE, the CMEPA and the amendatory laws in force to 1 August 2026, with a footnote at every provision naming the law that changed it.
The printed edition runs to 240 pages and carries the same text, footnotes and references as the browser below. Every section here shows the page it sits on in that PDF, so a citation taken from the screen matches the one taken from the book.
TITLE XIII — TAX INCENTIVES › CHAPTER I. GENERAL PROVISIONS ON TAX INCENTIVES
SEC. 293. Definitions
When used in this Title:
(A) Capital equipment refers to machinery, equipment, major components thereof, tools, devices, applications or apparatus, which are directly attributable to the registered project or activity of the registered business enterprise;
(B) Certificate of authority to import refers to the document issued by the Investment Promotion Agency as proof of entitlement to exemption from value-added tax and/or duty-free importation which shall contain a list of capital equipment, raw materials, spare parts, or accessories to be imported that are directly attributable to the production of goods and services, including goods used for administrative purposes;
(C) Certificate of registration refers to the document evidencing registration with an Investment Promotion Agency and entitlement to tax incentives: Provided, That each registered project or activity of a registered business enterprise should be supported by a separate certificate of registration;
(D) Directly attributable refers to goods and services that are incidental to and reasonably necessary for the registered project or activity of the registered business enterprise, including janitorial, security, financial, consultancy, marketing and promotion services, and services rendered for administrative operations such as human resources, legal, and accounting: Provided, That the determination of what is ‘directly attributable’ to the registered project or activity of the registered business enterprise shall be made by the relevant Investment Promotion Agency;
(E) Direct local employment refers to the full and decent employment of Filipinos by registered business enterprises under an employer-employee relationship to perform functions that are directly related to the production of goods or performance of services under the registered project or activity;
(F) Domestic input refers to purchases of locally manufactured goods or locally produced raw materials or domestically outsourced services known as services embedded in manufacturing that are used directly in the production of goods under the registered project or activity. In the case of locally manufactured goods, fifty percent (50%) of the value-added of the said good should likewise be locally produced or manufactured;
(G) Domestic market enterprise refers to any enterprise registered with the Investment Promotion Agency other than export enterprise;
(H) Export enterprise refers to any individual, partnership, corporation, Philippine branch of foreign corporation, or other entity organized and existing under Philippine laws and registered with the Investment Promotion Agency to engage in manufacturing, assembling or processing activity, and services such as information technology (IT) activities and business process outsourcing (BPO), and resulting in the direct exportation, and/or sale of its manufactured, assembled or processed product or IT/BPO services to another registered export enterprise that will form part of the final export product or export service of the latter, of at least seventy percent (70%) of its total production or output;
(I) Freeport zones refer to isolated and policed areas adjacent to a port of entry, which shall be operated and managed as a separate customs territory for purposes of ensuring free flow or movement of goods between registered business enterprises, except those expressly prohibited by law, within, into, and exported out of the freeport zone where imported goods may be unloaded for immediate transshipment or stored, repacked, sorted, mixed, or otherwise manipulated subject to the provisions of Sections 294(D) and (E) and 295(C) and (D): Provided, That a freeport shall have a permanent customs control or customs office at its perimeter;
(J) High-value domestic market enterprises refer to registered domestic market enterprises with an investment capital exceeding Fifteen billion pesos (Php15,000,000,000) and are engaged in sectors considered import-substituting, or with export sales in the immediately preceding year of at least One hundred million US dollars (USD100,000,000) or its equivalent in an acceptable foreign currency: Provided, That the threshold specified herein may be increased by the Fiscal Incentives Review Board;
(K) Investment capital refers to the value of investment indicated in Philippine currency, that shall be used to carry out a registered project or activity such as pre-operating expenses, cost of land and land improvements, buildings, leasehold improvements, working capital, machinery and equipment, inventory, and other current and non-current assets;
(L) Investment Promotion Agencies refer to government entities created by law, executive order, decree, or other issuances, in charge of promoting investments, granting and administering tax and non-tax incentives, and overseeing the operations of the different economic zones and freeports in accordance with their respective special laws. These include the Board of Investments (BOI), Bangsamoro Board of Investments (BBOI), Bangsamoro Economic Zone Authority (BEZA), Philippine Economic Zone Authority (PEZA), Bases Conversion and Development Authority (BCDA), Subic Bay Metropolitan Authority (SBMA), Clark Development Corporation (CDC), John Hay Management
Corporation (JHMC), Poro Point Management Corporation (PPMC), Cagayan Special Economic Zone Authority (CEZA), Zamboanga City Special Economic Zone and Freeport Authority (ZCSEZA), PHIVIDEC Industrial Authority (PIA), Aurora Pacific Economic Zone Authority (APECO), Authority of the Freeport Area of Bataan (AFAB), Tourism Infrastructure and Enterprise Zone Authority (TIEZA), Bulacan Special Economic Zone and Freeport Authority (BEZA), and all other similar existing authorities or those that may be created by law unless otherwise specifically exempted from the coverage of this Code.424
(M) Metropolitan areas refer to Metro Cebu and Metro Davao or those local government units which are later qualified or grouped as such by the National Economic and Development Authority or through laws or executive issuances;
(N) Net book value refers to historical cost less accumulated depreciation, as reflected in the books of account or financial statements of the registered business enterprise, and determined in accordance with accepted accounting standards;
(O) Other government agencies administering tax incentives refer to government agencies other than Investment Promotion Agencies which register or administer tax incentives of any kind to any specific entities and/or class of persons pursuant to any law;
(P) Other registered entities refer to any individual, partnership, organization, corporation, Philippine branch of a foreign corporation, or other entity incorporated and/or organized and existing under Philippine laws, and registered with other government agencies administering tax incentives;
(Q) Qualified capital expenditure refers to purchases of capital goods with a useful life or more than one (1) year acquired for the entity’s production of goods and services to be directly used in the project or activity of the registered business enterprise;
(R) Registered business enterprise refers to any individual, partnership, corporation, Philippine branch of a foreign corporation, or other entity organized and existing under Philippine laws and registered with an Investment Promotion Agency excluding service enterprises such as those engaged in customs brokerage, trucking or forwarding services, janitorial services, security services, insurance, banking, and other financial services, consumers’ cooperatives, credit unions, consultancy services, retail enterprises, restaurants, or such other similar services, as may be determined by the Fiscal Incentives Review Board, irrespective of location, whether inside or outside the zones, duly accredited or licensed by any of the Investment Promotion Agencies and whose income delivered within the economic zones shall be subject to taxes under the National Internal Revenue Code of 1997, as amended;
(S) Research and development refers to experimental or other related projects or activities:
(1) Whose outcome cannot be known or determined in advance on the basis of current knowledge, information or experience, but can only be determined by applying a systematic progression of work:
(i) Based on principles of established science; and
(ii) Proceeds from hypothesis to experiment, observation and evaluation, and leads to logical conclusions.
(2) That are conducted for the purpose of generating new knowledge, including new knowledge in the form of new or improved materials, products, devices, processes or services;
(T) Sophisticated refers to the state when a product or service requires a high level of technology, human capital, competencies or know-how, and infrastructure to be produced or offered;
(U) Sophistication refers to the level of technology, human capital, competencies or know-how, and infrastructure required for a product or service to be offered by an economy like that of the Philippines;
(V) Source document refers to input materials and documents reasonably needed by information technology (IT) and IT-enabled industries such as books, directories, magazines, newspapers, brochures, pamphlets, medical records or files, legal records or files, instruction materials, and drawings, blueprints, or outlines;
(W) Special economic zone or ecozone refers to a selected area which shall be operated and managed as a separate customs territory that is highly developed or has the potential to be developed into an agro-industrial, industrial, information technology, or tourist/recreational area, whose metes and bounds are fixed or delimited by presidential proclamations and is within a specific geographical area which includes industrial estates (IEs), export processing zones (EPZs), ICT parks and centers, and free trade zones: Provided, That for the ecozone to qualify as a separate customs territory, an ecozone shall have a permanent customs control or customs office at its perimeter: Provided, however, That areas where mining extraction is undertaken shall not be declared as an ecozone: Provided, further, That vertical economic zones, such as, but not limited to, buildings, selected floors within buildings, and selected areas on a floor, need to comply with the minimum contiguous land area as determined by the Fiscal Incentives Review Board;
(X) Technical obsolescence refers to the state of an asset when its design or specification no longer fulfills the function for which it was originally designed and/or the machinery, equipment, spare parts and/or materials have diminished in value as caused by changes in technology and new inventions, rendering it less desirable in the industry, including a decline in value due to the availability of improved, more cost-effective alternatives, or due to the availability of more advanced technology that allows for more efficiency such as earlier replacement of information technology assets, as may be verified and approved by the Investment Promotion Agency; and
(Y) Training refers to courses, curricula, certifications or modules provided to Filipino employees that are directly related to the production of goods or performance of services under the registered project or activity and that are of a technical nature, which shall develop or improve the specific skills or practical knowledge of the employee especially in the mechanical, industrial art, scientific field or practical science of a particular position or job function in the registered project or activity, or in preparation for enhancing the value chain.
Amendment notes
- CREATE MORE Act (RA 12066), sec. 16, approved 8 November 2024 — amended. The Act re-lettered the definitions in this Section: the subsections that previously appeared as (B) to (S) now appear as (E) to (Y), and seven definitions were added — certificate of authority to import, certificate of registration, directly attributable, high-value domestic market enterprises, investment capital, net book value, and technical obsolescence. The definitions of capital equipment, freeport zones, Investment Promotion Agencies and special economic zone were rewritten; the remainder were carried forward unchanged, the Act printing them as "x x x". Readers working from documents that cite this Section by subsection letter should check the letter against the version in force at the relevant time. The subsection vetoed by the President when the CREATE Act was signed does not appear in the Section as re-enacted.
- The acronym "(BEZA)" appears twice in this subsection as enacted, first for the Bangsamoro Economic Zone Authority and again for the Bulacan Special Economic Zone and Freeport Authority. The text is reproduced as it appears in the enrolled text of the Act.