What we do
Full-service assurance, tax, and advisory.
From statutory audit to strategic advisory, our engagements are built on rigor, ethics, and a genuine understanding of your business.
Audit & Assurance
- Financial statements audit
- Internal audit
- Review of historical financial statements
- Review of prospective financial statements
Tax Services
- Tax assessment
- Tax compliance health check
- Tax due diligence
- Tax opinions and rulings
- Tax planning and structuring
- Estate and donor’s tax compliance
Accounting Services
- Bookkeeping
- Compilation of financial statements
- Account reconciliations
- Internal accounting
Advisory & Business Consultancy
- Business policy making
- Financial due diligence
- Risk management
- Strategic management
Corporate Services
- Business registration
- Corporate structuring
- Corporate secretarial
- Payroll processing and compliance
Other Services
- Agreed-upon procedures
- Company profiling & loan application assistance
- Estate planning · Retirement planning and funding
- Contract review · Collection services
- Real estate services and other allied services
Who we serve
Industries we serve.
The reporting framework, the controls, and the regulator differ by sector. Our engagements cover twelve.
Beyond Tacloban City
Engagements run from wherever you are.
Clients elsewhere in Eastern Visayas, in Metro Manila and in other regions work with us without travelling to our office.
Documents turned over online
Records, schedules and supporting documents are exchanged through shared online folders, and reports are delivered the same way.
Meetings by video call
Planning, status and closing meetings are held by video call. Visits are scheduled where the work requires them, such as an inventory count.
Electronic filing
Returns and reports are filed through the online systems of the BIR, the SEC and the other agencies that accept them.
Our Partners
Led by credentialed professionals.
Four partners with national distinctions, international practice, and deep roots in the academe.
Placed 2nd in the May 2018 CPA licensure examination. Trained in assurance and taxation at one of the largest professional services firms in the world before returning to Region VIII, and has since audited MSMEs through to large corporations. Assists taxpayers through BIR audits and assessments. Teaches audit, assurance, and taxation, and authored a CPA reviewer book on auditing.
View full profile →
Audit and Professional Practice Director at one of the world’s Top 4 professional services firms, serving in its London, New York, and Philippine offices. Sat three consecutive terms on the Audit and Assurance Standards Council, served as National President of PICPA for FY 22-23, and sits on the council of the ASEAN Federation of Accountants. Led Saint Paul School of Professional Studies as President for more than a decade.
View full profile →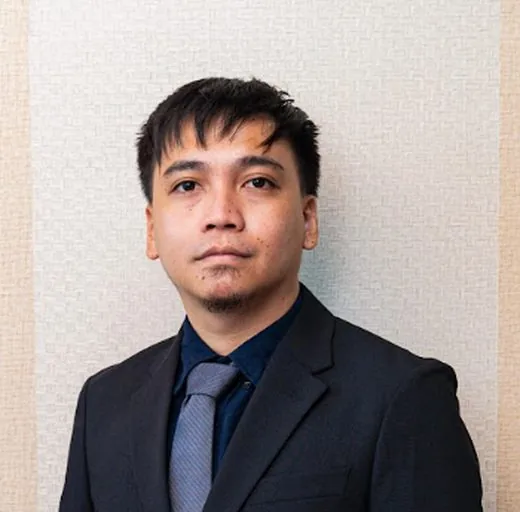
Placed 1st in the May 2018 CPA licensure examination and 10th in the December 2023 Bar. Practice centres on tax compliance and health checks, assistance with tax audits, corporate structuring, and tariff and customs compliance. Began his career as a risk and compliance officer, internal auditor, and data privacy officer. Lectures on taxation and commercial law and reviews for the CPA board examinations.
View full profile →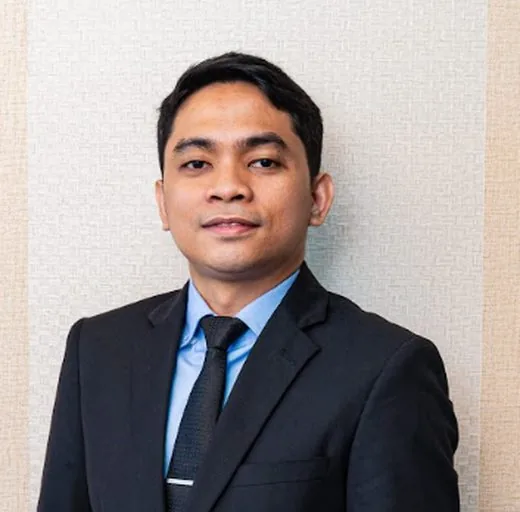
More than half a decade in the public practice of accountancy, auditing MSMEs and large corporations across retail and trade, educational institutions, non-profits, importation, and services. Began as an audit associate at a Manila firm. Works in full-cycle accounting and financial reporting with variance and ratio analysis. School accountant and part-time lecturer at SPSPS, and treasurer of PICPA–Tacloban Chapter.
View full profile →Insights
What falls due this month.
The next filing and payment deadlines we are tracking. Open the calendar for the full year.
Get in touch
Let’s talk about your business.
Tell us what you need — audit, tax, bookkeeping, or advisory — and our team will get back to you.
2nd Floor, Rubber Tree Building, Brgy. 77, 611 BLISS – Fatima Diversion Road, Tacloban City, Philippines 6500
Suite 302, F. Mendoza Complex, Sto. Niño St., Brgy. 28, Tacloban City 6500
0995 398 9482
info@aaccocpas.com
Message us on Messenger
Insights
AAC Tax Code.
The National Internal Revenue Code of 1997 as it currently stands — consolidated by the firm to carry the TRAIN Law, the CREATE Act, the Ease of Paying Taxes Act, the VAT on Digital Services Act, CREATE MORE, the CMEPA and the amendatory laws in force to 1 August 2026, with a footnote at every provision naming the law that changed it.
The printed edition runs to 240 pages and carries the same text, footnotes and references as the browser below. Every section here shows the page it sits on in that PDF, so a citation taken from the screen matches the one taken from the book.
TITLE II — TAX ON INCOME › CHAPTER I. — DEFINITIONS
SEC. 22. Definitions
When used in this Title:
(A) The term ‘person’ means an individual, a trust, estate, or corporation.
(B) The term ‘corporation’ shall include one person corporations,12 partnerships, no matter how created or organized, joint-stock companies, joint accounts (cuentas en participacion), associations, or insurance companies, but does not include general professional partnerships and a joint venture or consortium formed for the purpose of undertaking construction projects or engaging in petroleum, coal, geothermal and other energy operations pursuant to an operating or consortium agreement under a service contract with the Government. ‘General professional partnerships’ are partnerships formed by persons for the sole purpose of exercising their common profession, no part of the income of which is derived from engaging in any trade or business.
(C) The term ‘domestic’, when applied to a corporation, means created or organized in the Philippines or under its laws.
(D) The term ‘foreign’, when applied to a corporation, means a corporation which is not domestic.
(E) The term ‘nonresident citizen’ means:
(1) A citizen of the Philippines who establishes to the satisfaction of the Commissioner the fact of his physical presence abroad with a definite intention to reside therein.
(2) A citizen of the Philippines who leaves the Philippines during the taxable year to reside abroad, either as an immigrant or for employment on a permanent basis.
(3) A citizen of the Philippines who works and derives income from abroad and whose employment thereat requires him to be physically present abroad most of the time during the taxable year.
(4) A citizen who has been previously considered as nonresident citizen and who arrives in the Philippines at any time during the taxable year to reside permanently in the Philippines shall likewise be treated as a nonresident citizen for the taxable year in which he arrives in the Philippines with respect to his income derived from sources abroad until the date of his arrival in the Philippines.
(5) The taxpayer shall submit proof to the Commissioner to show his intention of leaving the Philippines to reside permanently abroad or to return to and reside in the Philippines as the case may be for purposes of this Section.
(F) The term ‘resident alien’ means an individual whose residence is within the Philippines and who is not a citizen thereof.
(G) The term ‘nonresident alien’ means an individual whose residence is not within the Philippines and who is not a citizen thereof.
(H) The term ‘resident foreign corporation’ applies to a foreign corporation engaged in trade or business within the Philippines.
(I) The term ‘nonresident foreign corporation’ applies to a foreign corporation not engaged in trade or business within the Philippines.
(J) The term ‘fiduciary’ means a guardian, trustee, executor, administrator, receiver, conservator or any person acting in any fiduciary capacity for any person.
(K) The term ‘withholding agent’ means any person required to deduct and withhold any tax under the provisions of Section 57.
(L) The term ‘shares of stock’ shall refer to shares of stock of a corporation, warrants, options, as well as units of participation in partnerships (except general professional partnerships), joint stock companies, joint accounts, joint ventures taxable as corporations, associations, and recreation or amusement clubs (such as golf, polo or similar clubs), and mutual fund certificates.13
(M) The term ‘shareholder’ shall refer to a holder of shares of stock, warrants, options, as well as a holder of a unit of participation, in a partnership (except general professional partnership), joint stock company, joint account, taxable joint venture, and holder of a mutual fund certificate, joint stock company, or insurance company, or member in an association, recreation, or amusement club, such as golf, polo, or similar clubs.14
(N) The term ‘taxpayer’ means any person subject to tax imposed by this Title.
(O) The terms ‘including’ and ‘includes’, when used in a definition contained in this Title, shall not be deemed to exclude other things otherwise within the meaning of the term defined.
(P) The term ‘taxable year’ means the calendar year, or the fiscal year ending during such calendar year, upon the basis of which the net income is computed under this Title. ‘Taxable year’ includes, in the case of a return made for a fractional part of a year under the provisions of this Title or under rules and regulations prescribed by the Secretary of Finance, upon recommendation of the Commissioner, the period for which such return is made.
(Q) The term ‘fiscal year’ means an accounting period of twelve (12) months ending on the last day of any month other than December.
(R) The terms ‘paid or incurred’ and ‘paid or accrued’ shall be construed according to the method of accounting upon the basis of which the net income is computed under this Title.
(S) The term ‘trade or business’ includes the performance of the functions of a public office.
(T) The term ‘securities’ shall refer to shares, participation, or interest in a corporation, commercial enterprise, or profit-making venture evidenced by a certificate, contract, or instrument, whether written or electronic in character, which shall include:15
(1) Shares of stock, bonds, debentures, notes, evidence of indebtedness, and asset-backed securities;
(2) Investment contracts, certificates of interest, or participation in a profit-sharing agreement, such as certificates of deposit for a future subscription;
(3) Fractional undivided interests in oil, gas, or other mineral rights;
(4) Certificates of assignment, certificates of participation, trust certificates, voting trust certificates, or similar instruments;
(5) Proprietary or non-proprietary membership certificates in corporations; and
(6) Other similar instruments as may be determined by the Securities and Exchange Commission.
(U) The term ‘dealer in securities’ means a merchant of stocks or securities, whether an individual, partnership or corporation, with an established place of business, regularly engaged in the purchase
of securities and the resale thereof to customers; that is, one who, as a merchant, buys securities and re-sells them to customers with a view to the gains and profits that may be derived therefrom.
(V) The term ‘bank’ means every banking institution, as defined in Section 2 of Republic Act No. 337, as amended, otherwise known as the General Banking Act. A bank may either be a commercial bank, a thrift bank, a development bank, a rural bank or a specialized government bank.
(W) The term ‘non-bank financial intermediary’ means a financial intermediary, as defined in Section 2(D)(c) of Republic Act No. 337, as amended, otherwise known as the General Banking Act, authorized by the Bangko Sentral ng Pilipinas (BSP) to perform quasi-banking activities.
(X) The term ‘quasi-banking activities’ means borrowing funds from twenty (20) or more personal or corporate lenders at any one time, through the issuance, endorsement, or acceptance of debt instruments of any kind other than deposits for the borrower’s own account, or through the issuance of certificates of assignment or similar instruments, with recourse, or of repurchase agreements for purposes of relending or purchasing receivables and other similar obligations: Provided, however, That commercial, industrial and other non-financial companies, which borrow funds through any of these means for the limited purpose of financing their own needs or the needs of their agents or dealers, shall not be considered as performing quasi-banking functions.
(Y) The term ‘deposit substitute’ shall refer to an alternative form of obtaining funds from the public other than deposits, through the issuance, endorsement, or acceptance of debt instruments for the borrower’s own account, for the purpose of relending or purchasing of receivables and other obligations: Provided, That the term ‘public’ shall mean twenty (20) or more individual or corporate lenders at any given time. These instruments may include, but need not be limited to, bankers’ acceptances, promissory notes, repurchase agreements, excluding reverse repurchase agreements entered into by and between the Bangko Sentral ng Pilipinas (BSP) and any authorized agent bank, certificates of assignment or participation, and similar instruments with recourse: Provided, however, That debt instruments issued for interbank call loans with maturity of not more than five (5) days to cover deficiency in reserves against deposit liabilities, including those between or among banks and quasi-banks, shall not be considered as deposit substitute debt instruments.16
(Z) The term ‘ordinary income’ includes any gain from the sale or exchange of property which is not a capital asset or property described in Section 39(A)(1). Any gain from the sale or exchange of property which is treated or considered, under other provisions of this Title, as ‘ordinary income’ shall be treated as gain from the sale or exchange of property which is not a capital asset as defined in Section 39(A)(1). The term ‘ordinary loss’ includes any loss from the sale or exchange of property which is not a capital asset. Any loss from the sale or exchange of property which is treated or considered, under other provisions of this Title, as ‘ordinary loss’ shall be treated as loss from the sale or exchange of property which is not a capital asset.
(AA) The term ‘rank and file employees’ shall mean all employees who are holding neither managerial nor supervisory position as defined under existing provisions of the Labor Code of the Philippines, as amended.
(BB) The term ‘mutual fund company’ shall mean an open-end and close-end investment company as defined under the Investment Company Act.
(CC) The term ‘trade, business or profession’ shall not include performance of services by the taxpayer as an employee.
(DD) The term ‘regional or area headquarters’ shall mean a branch established in the Philippines by multinational companies and which headquarters do not earn or derive income from the Philippines and which act as supervisory, communications and coordinating center for their affiliates, subsidiaries, or branches in the Asia-Pacific Region and other foreign markets.
(EE) The term ‘regional operating headquarters’ shall mean a branch established in the Philippines by multinational companies which are engaged in any of the following services: general administration and planning; business planning and coordination; sourcing and procurement of raw materials and components; corporate finance advisory services; marketing control and sales promotion; training and personnel management; logistic services; research and development services and product development; technical support and maintenance; data processing and communication; and business development.
(FF) The term ‘long-term deposit or investment certificate’ shall refer to certificate of time deposit or investment in the form of savings, common or individual trust funds, deposit substitutes, investment management accounts and other investments with a maturity period of not less than five (5) years, the form of which shall be prescribed by the Bangko Sentral ng Pilipinas (BSP) and issued by banks only (not by nonbank financial intermediaries and finance companies) to individuals in denominations of Ten thousand pesos (P10,000) and other denominations as may be prescribed by the BSP.
(GG) The term ‘statutory minimum wage’ shall refer to the rate fixed by the Regional Tripartite Wage and Productivity Board, as defined by the Bureau of Labor and Employment Statistics (BLES) of the Department of Labor and Employment (DOLE).
(HH) The term ‘minimum wage earner’ shall refer to a worker in the private sector paid the statutory minimum wage, or to an employee in the public sector with compensation income of not more than the statutory minimum wage in the non- agricultural sector where he/she is assigned.
(KK) The term ‘filing of return’ shall refer to the act of accomplishing and submitting the prescribed tax return, electronically or manually, to the Bureau of Internal Revenue, or through any authorized agent bank or authorized tax software provider, as required under this Code or as prescribed under existing rules and regulations.17
(LL) The terms ‘payment of tax’ or ‘remittance of tax’ shall refer to the act of delivering the amount of tax due or withheld, either electronically or manually, to the Bureau of Internal Revenue, or through any authorized agent bank or authorized tax software provider, as required under this Code or as prescribed under existing rules and regulations.18
(MM) The term ‘passive income’ shall refer to any income that is earned from sources that do not require a taxpayer’s active pursuit and performance of trade or business and is not subject to value-added tax imposed in this Code.19
Amendment notes
- Subsections (II) and (JJ), defining "offshore gaming licensee" and "offshore gaming licensee-gaming agent", were introduced by sec. 2 of Republic Act No. 11590, approved 22 September 2021. Republic Act No. 11590 was repealed in its entirety by sec. 18 of Republic Act No. 12312, the Anti-POGO Act of 2025, approved 23 October 2025, which bans and criminalises offshore gaming operations. The amendments it introduced are accordingly spent. Republic Act No. 12312 contains no clause reviving the text that preceded them.
- CREATE Act, sec. 4 — amended.
- Capital Markets Efficiency Promotion Act (RA 12214), sec. 3, approved 29 May 2025 — amended.
- Capital Markets Efficiency Promotion Act (RA 12214), sec. 3, approved 29 May 2025 — amended.
- Capital Markets Efficiency Promotion Act (RA 12214), sec. 3, approved 29 May 2025 — amended.
- Capital Markets Efficiency Promotion Act (RA 12214), sec. 3, approved 29 May 2025 — amended.
- Introduced by sec. 4 of the Ease of Paying Taxes Act, which designated these definitions as Subsections (KK) and (LL). Subsections (II) and (JJ) do not appear in the Code as consolidated; the lettering gap is reproduced as enacted.
- Ease of Paying Taxes Act, sec. 4 — inserted.
- Capital Markets Efficiency Promotion Act (RA 12214), sec. 3, approved 29 May 2025 — inserted. The Act adds a definition of passive income for the purposes of this Title.